
The AI Boom Has a Rate Problem
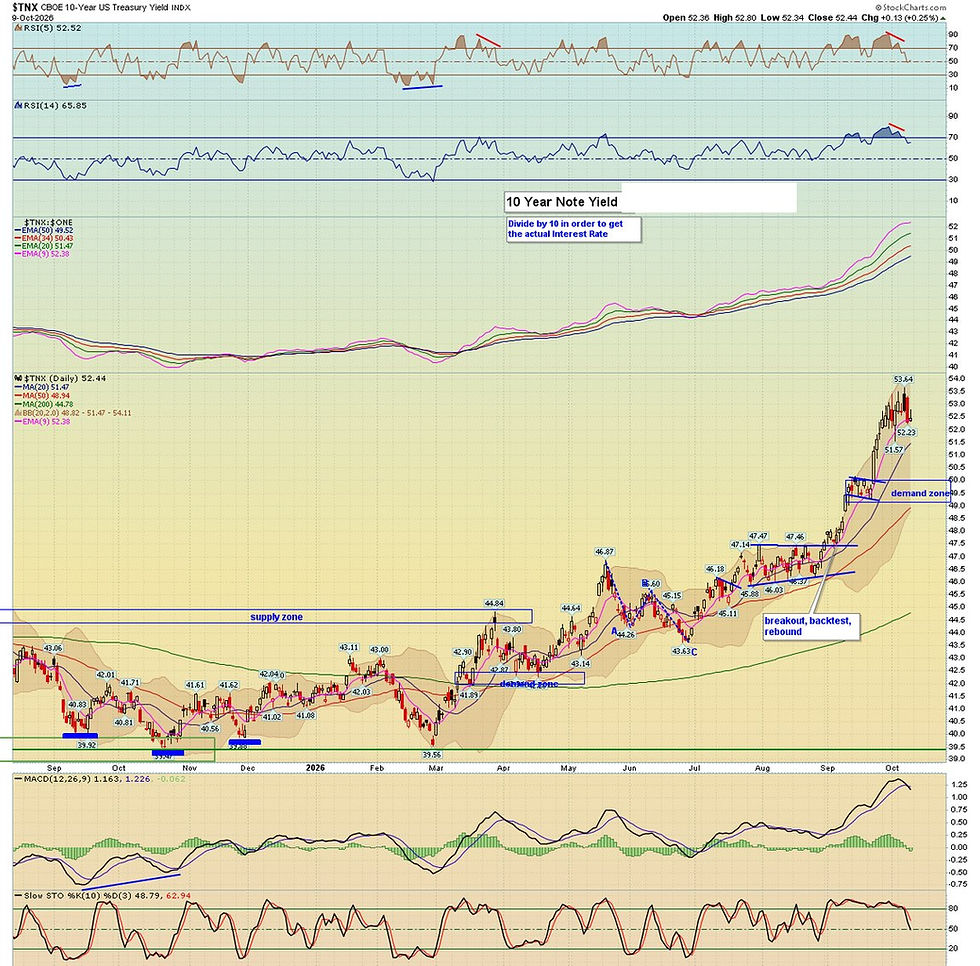
Stocks and gold are getting some relief this morning as yields back off. Fine. Take the win. Just do not mistake a morning breather for the end of the higher-rate era.
One line from this morning's rates piece sums up the problem perfectly:
“When debt, deficits and external financing needs collide, markets tend to become far less forgiving.”
That is the whole movie. Governments are already issuing mountains of debt. Companies still need to refinance. Consumers are carrying higher loan costs. And now the AI build-out is stepping into the same capital market with a blank check and a hard hat.
Data centers, power, cooling, chips, memory, grid upgrades — this is not a cute little software cycle. It is physical infrastructure. Physical infrastructure eats capital. Lots of it.
Rate Pressure Stack
Government refinancing — the biggest claim on long-term capital
AI infrastructure borrowing — data centers, power, chips, and grid upgrades competing for the same funding pool
Inflation / oil risk — keeps the Fed and the bond market honest
Equity valuation sensitivity — distant cash flows and heroic growth assumptions feel gravity first
Simple framework: the more borrowers fighting for long-term capital, the harder it is for yields to fall and stay down.
Why This Matters for Investors
Higher long-term yields do not hit every asset equally. They are especially annoying for the parts of the market priced on distant cash flows, cheap leverage, or heroic growth assumptions. Translation: the stuff Wall Street loves to pretend has no gravity.
The AI trade can still be real. I am not arguing against the build-out. I am saying the build-out has a financing side, and the financing side matters. Before AI becomes deflationary through productivity, it may be inflationary through demand for power, copper, memory, equipment, and capital.
That is why I would be careful chasing every relief rally as if the bond market just waved the all-clear flag. One good morning in yields is not a regime change.
Hans's Take
Enjoy the relief rally. Just do not confuse lower yields this morning with the end of the higher-rate regime.
The AI build-out may be productivity bullish long term, but it is capital-hungry right now. That makes it harder for rates to fall and stay down.
Portfolio Read-Through
For income traders: higher yields can support premium, but they also raise the cost of being wrong. Guardrails matter.
For LEAPS: duration still matters. Great companies can still get repriced if discount rates stay elevated.
For AI winners: separate businesses funding the boom from businesses merely narrating the boom. Big difference.
Trade smart, stay hedged.
Hans Albrecht • Options With Hans
Educational content only. Not financial advice. Options involve risk and are not suitable for every investor.
Comments